A hail damage roof inspection is about two things that matter right now, keeping water out of your house and not getting shorted on an insurance claim. After a hailstorm, some people panic and sign with the first roofer at the door, others ignore the roof until a brown stain creeps across the ceiling.
What you actually need is a calm, repeatable way to check for damage, document what you find, and decide whether you are looking at a small repair, a full replacement, or a real dispute with your carrier. We will walk through the practical parts so you can talk to adjusters and contractors with confidence instead of guessing from the driveway, and you can compare what you see with the examples in Storm Damage & Insurance.
What Hail Really Does To A Roof
Hail does not care how proud you are of the shingles, but age changes how badly they respond. Newer shingles tend to bruise and lose granules, older shingles are more likely to crack right through and shed pieces into your gutters.
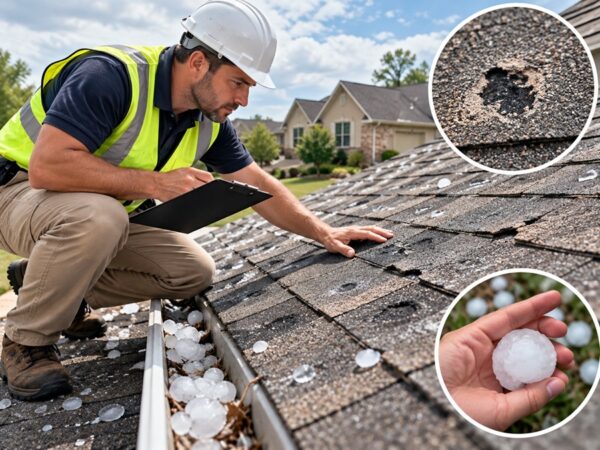
On an asphalt hail damage roof the problems we see most are soft bruises and bare spots where black asphalt shows through. Metal, tile and flat roofs also take a beating, but the damage looks different and is easier to miss if you only know what asphalt bruises look like, so it helps to read posts like Roof Cleaning to tell normal surface wear from real impact damage.
Safety First Before You Check Anything
The first step in how to check roof for hail damage is deciding whether you should even leave the ground. If the roof is steep, wet or covered in loose debris, stay off it and inspect from ladders and the yard instead.
From the ground, walk the perimeter and look for torn window screens, dented gutters and damage to soft metal like downspouts or AC units, because those are quick indicators of how hard the hail hit. If you already have interior leaks or broken glass, make temporary covers your first priority, then circle back to photos and notes once things are safe, or call the number under Contact Us if you need a roofer fast.
Step By Step Hail Inspection At Home
When you are ready to inspect, work in a slow pattern instead of hopping straight to the spots you are worried about. Take photos from the same direction each time so an adjuster can follow your path later if a claim enters the picture.
If you are comfortable on a ladder, check the lower edges and one or two accessible slopes instead of climbing to the very top. Many homeowners are surprised later when a pro finds damage right at the eaves that had been overlooked during a quick look from the peak, so limit yourself to what you can reach safely and leave the high work for a contractor.
Checking Shingles Up Close
The clearest signs of hail damage on roof shingles are circular impact marks, soft bruises you can feel when you press gently, and spots where granules are knocked away to reveal dark asphalt. If you see shiny, torn or cracked edges, those shingles have probably lost their weather seal and may lift in the next wind.
Do not start picking at bruises or lifting shingles to see how bad they are, because that can turn borderline damage into a real problem and hand your insurer an excuse to say you made it worse. Instead, stand back a few feet and take clear photos in good light from different angles so anyone reviewing them later understands what you saw that first day, then compare what you are seeing with example photos in posts such as File a Roof Insurance Claim After a Storm (Step-by-Step).
What To Photograph And How
For every slope that looks affected, get a wide shot and then several close ups with something in frame for scale, like a tape measure or your hand. Include at least one photo that shows the whole slope from edge to ridge so anyone reviewing can tell exactly where those close ups belong.
When you step back down, take pictures of dented gutters, downspouts and any hail still on the ground if it has not melted yet. If you later decide to file a claim, it helps more than you think to show the adjuster what size hail actually fell at your house, especially if your file ends up alongside other homes from the same storm.
Documenting For Insurance From Day One
Even if you are not sure yet that you will file, set up a simple folder on your phone or computer with the storm date, photos and any notes about leaks or interior damage. Insurers like timelines, and you will like having that timeline on your side if a claim turns into a dispute and you are reading through resources such as Insurance Denied Your Roof Claim.
Keep receipts for tarps, temporary repairs or emergency visits, because those out of pocket costs can sometimes be part of a future reimbursement. A short written log with dates, what you saw and who you spoke with at the carrier saves you from trying to remember details months later when specific numbers and names really matter.
When To Call A Pro And What To Expect
Call a qualified roofer when your own check turns up bruised shingles in different areas, when you see active leaks, or when you are not comfortable climbing at all. A good contractor will do more than glance at the roof, they will check attic spaces, ventilation and past repair spots that are likely weak points.
Many roofers offer a free or low cost inspection after storms, but the value is in how thorough they are and how clearly they explain what they find. Look for someone who can walk you through photos and a written summary instead of just saying you need a new roof without backing it up, and compare what they say with cost ranges in articles such as It Cost to Replace a 2,000 Sq Ft Roof so the recommendation matches your budget and roof size.
How Hail Damage Ties Into Insurance And Claims
Insurance policies usually cover sudden accidental damage, which is where hail fits, but every policy has its own limits and exclusions. Before you call your carrier, skim your declarations page for your wind and hail deductible so you have a rough sense of the cost share they expect.
When you are talking with your insurer about inspection and next steps, ask plainly whether they want you to get contractor estimates first or whether they will send an adjuster out. Different companies handle that order in different ways, and getting it wrong can create headaches later that have nothing to do with the actual roof.
Working With The Adjuster
When an adjuster visits, your job is to be ready with your photos, notes and any contractor reports you already have. Walk the exterior with them if they allow it and politely point out the areas you are concerned about instead of assuming they will see everything on their own.
If they decide some slopes qualify and others do not, ask them to explain the difference on the spot so you understand their reasoning. That conversation is much easier in real time on the roof than after you get a short letter by mail that lays out a decision you do not agree with.
If The Claim Is Denied Or Underpaid
Not every denial or low estimate is final, and many homeowners give up too early. If your adjuster says the roof only has cosmetic damage but your contractor disagrees, ask for a reinspection and gather more documentation rather than arguing by phone.
You can learn your options for second opinions, appraisals or complaints from resources like Insurance Denied Your Roof Claim. Stay organized and stick to facts about what is damaged and what it takes to restore the roof to its pre storm condition, because that is what most policies promise to address.
Repair, Replace, Or Wait It Out
Once you have a clear picture of the damage and what insurance will or will not cover, you are basically choosing between repair, replacement or monitoring. Small, isolated impacts on an otherwise young roof can often be handled by swapping individual shingles or patching specific sections.
If the roof is near the end of its life or damage is scattered across many slopes, a full replacement usually makes more financial sense than chasing leaks one by one. Articles like Signs You Need a Roof Replacement (Not Just a Repair) can help you see where you are on that spectrum so you do not spend good money tracking down new drips every few months.
Thinking About Future Resale And Timing
Hail does not care about your moving plans, but buyers will care about the condition and age of the roof they inherit. If you plan to sell within a few years, a documented recent replacement can be a strong selling point, while an obviously bruised roof can drive offers down.
So weigh timing carefully before declining a reasonable settlement or putting off work for too long. A tired roof with visible storm wear will not get better with time, and it will not impress a home inspector either, which matters if a future buyer asks about a hail damage roof insurance claim that shows up in your paperwork.
Conclusion
A careful hail damage roof inspection is about protecting your house and the claim tied to it. When you know what to look for, how to document it and when to push back on a weak estimate, you give yourself options that rushed decisions never leave you.
If you are staring at a post storm roof and are not sure what comes next, get qualified eyes on it and use the resources from Roofing Cop to plan your next step with your insurer and contractor.
Frequently Asked Questions
Q1. How soon after a hailstorm should I check my roof
Ans. You should check your roof as soon as it is safe to go outside and the hail has stopped. Early photos and notes help if you decide to file a claim later. Just avoid climbing on a wet or slick surface and start from the ground if needed.
Q2. Can small hail still damage my roof
Ans. Yes, even small hail can damage older or already worn shingles, especially if it falls for a long time with strong wind. The impacts may be more subtle, like extra granules in gutters or soft bruises instead of obvious breaks. A careful inspection is the only way to tell.
Q3. Do I need to replace the whole roof for hail damage
Ans. Not always, because some roofs only have damage on a few slopes or in specific areas. If the roof is relatively new and the impacts are limited, repairs might be enough. A contractor and adjuster should both explain why they recommend repair or replacement.
Q4. Will my insurance premium go up if I file a hail claim
Ans. Filing a hail claim can affect premiums, but it depends on your carrier and state rules. Many insurers treat hail as a weather event that affects whole areas, not just you. It is worth asking your agent how your company typically handles storm claims before you decide.
Q5. How do I know if a roofer is qualified to inspect hail damage
Ans. A qualified roofer should be licensed where required, insured and willing to show photos and written findings. They should answer your questions clearly without pressuring you to sign anything on the spot. Local experience with insurance work is a plus but not the only factor.
Q6. Can I clean my gutters and roof right after hail before an inspection
Ans. It is better to document first and clean second, especially if you may file a claim. Once you clear granules out of gutters or remove damaged pieces, those signs are gone for good. Take photos, then go ahead and clean for safety and drainage.